KYC and AML in iGaming: Compliance Without Friction
A practical guide for iGaming operators to identity checks, risk-based AML controls, source of funds reviews and smoother player journeys.
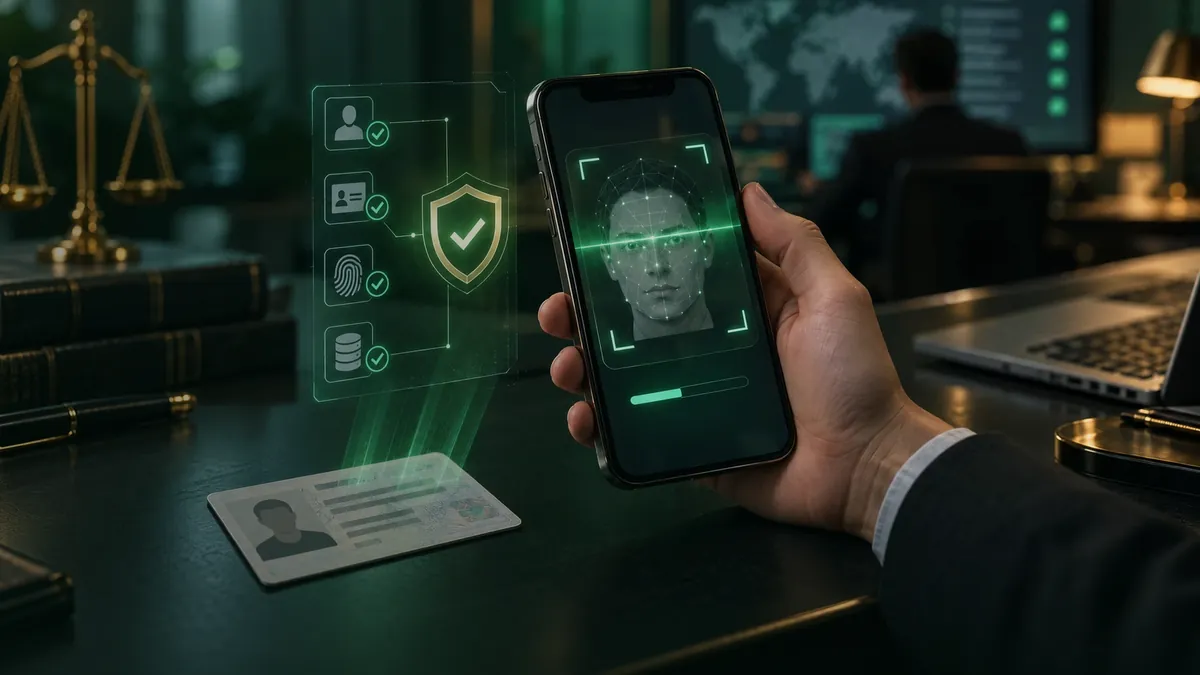
Players abandon verification when requirements feel confusing, repetitive or poorly timed. Yet letting them move through your casino or sportsbook without the required checks exposes the business to regulatory action, financial crime and avoidable payment disputes. The operational challenge is to make legitimate access straightforward while detecting situations that need closer review.
That balance depends on more than selecting a document-checking supplier. You need clear rules for when verification happens, how risk changes over time, who reviews alerts and what players see when something goes wrong. This is not legal advice; check current requirements with the official regulator in each target jurisdiction.
1. Establish the compliance baseline before designing the journey
KYC, or know your customer, establishes who a player is and supports checks such as age and identity verification. AML, or anti-money laundering, extends beyond onboarding to assess financial-crime risk, monitor activity and escalate suspicious behaviour. They overlap, but an approved identity document does not make every subsequent transaction low risk.
Requirements differ by licensing jurisdiction, operator type and product. Some markets require verification before gambling; others impose specific restrictions on deposits, account access or withdrawals until defined checks are complete. Do not assume that a process accepted under one licence can be reused unchanged elsewhere.
Turn obligations into operational rules
Build a jurisdiction-specific control matrix covering:
- Required identity attributes, age checks and verification timing.
- Customer due diligence and enhanced due diligence triggers.
- Sanctions screening and politically exposed person assessment.
- Record retention, privacy obligations and reporting routes.
- Ownership of decisions, exceptions and regulatory submissions.
Give each rule an accountable owner and an implementation location: registration, cashier, monitoring engine or case-management workflow. This makes gaps easier to identify than a policy document that says only that the operator takes a risk-based approach.
2. Build identity verification around clear decision points
A useful onboarding flow collects only the information needed at that stage, checks it against reliable sources and explains any additional request. Verification can use electronic data checks, identity documents and, where lawful and appropriate, selfie or liveness checks. No single method is equally suitable for every country or customer.
A practical verification sequence
- Collect core details: request the required name, date of birth, address and other identifying information.
- Validate the information: identify incomplete entries, inconsistencies and potential duplicate accounts.
- Verify identity and age: use approved sources and document checks appropriate to the market.
- Perform relevant screening: assess sanctions matches and politically exposed person results under applicable rules.
- Resolve exceptions: route uncertain results to trained reviewers rather than treating every mismatch as fraud.
- Record the outcome: retain the decision, supporting evidence and applicable policy version.
Payment-account ownership checks can help identify third-party funding, but payment authentication should not automatically be treated as complete identity verification.
Names with different transliterations, recently changed addresses and unsupported documents can create false failures. Provide an accessible alternative route and clear upload instructions. Players should know what is needed, why it is needed at a general level and how to contact support without receiving sensitive details about internal detection rules.
3. Apply risk-based controls without weakening mandatory checks
A risk-based approach allocates additional scrutiny according to the customer's profile and behaviour. It does not allow an operator to skip legally required checks because a player deposits a small amount or passes an automated score.
Assess factors such as geographic exposure, product use, payment methods, account relationships and unusual transaction patterns. Keep the model explainable enough for reviewers to understand why a case was escalated. Reassess risk when relevant information changes rather than relying permanently on the onboarding result.
| Risk situation | Appropriate operational response | Player-experience consideration |
|---|---|---|
| Consistent identity and ordinary activity | Complete required checks and continue ongoing monitoring | Avoid requesting documents already verified and still valid |
| Unresolved identity discrepancy | Request targeted evidence or conduct manual review | Explain the specific correction or document needed |
| Potential sanctions match | Resolve the match and apply legally required restrictions or escalation | Avoid disclosing sensitive screening logic |
| Politically exposed person identified | Apply required enhanced due diligence, approvals and monitoring | Do not imply that this status alone establishes wrongdoing |
| Unusual funding or transaction pattern | Review activity and request proportionate evidence where needed | Use one coordinated request rather than repeated messages |
Separate related decisions
AML, fraud prevention and responsible gambling may identify overlapping signals, but they answer different questions. A sudden increase in deposits could warrant both a financial-crime review and a player-protection intervention. Passing a source of funds check does not establish that gambling is affordable or safe. Keep the relevant assessments and decision records distinct, even when teams share information lawfully.
4. Make source of funds checks specific and proportionate
Source of funds concerns the origin of money used for particular transactions or gambling activity. Source of wealth concerns how a customer accumulated their overall wealth. Confusing the two often produces excessive document requests and weak conclusions.
Depending on the circumstances, useful evidence might include salary records, bank statements showing relevant income, business distributions, investment proceeds or documents supporting an asset sale. The required evidence should match the explanation, the risk and local rules; there is no universal document pack suitable for every player.
Review the explanation, not just the upload
A reviewer should ask whether the evidence supports the stated funding source and connects plausibly to the funds reaching the account. Check relevant dates, ownership and unexplained transfers. A bank statement showing a balance may not explain where that balance came from.
To reduce unnecessary friction:
- Explain which funding source needs evidence and list suitable alternatives.
- Request only the relevant period and information, subject to local requirements.
- Permit appropriate redaction where it does not prevent assessment.
- Combine outstanding questions into one request where possible.
- Use secure uploads with controlled access rather than informal channels.
Document the rationale for accepting evidence, requesting more information or applying account restrictions. Inconclusive evidence needs a defined escalation path, not indefinite requests from different teams.
5. Connect monitoring, investigation and reporting
Transaction monitoring should consider deposits, withdrawals, wagering and payment behaviour together. Looking only at transaction size can miss patterns involving linked accounts, repeated payment-method changes or funds entering and leaving with limited gambling activity.
Potential indicators include rapid deposit-and-withdrawal cycles, apparent third-party funding, attempts to bypass controls and activity inconsistent with the customer's known profile. These are reasons to investigate, not automatic proof of money laundering. Sportsbook and casino activity may require different scenarios because their wagering patterns differ.
Give every alert a usable workflow
An effective process includes alert prioritisation, an assigned reviewer, access to relevant evidence, a documented decision and escalation criteria. Test monitoring rules against actual cases and review false positives. Reducing alert volume is useful only if detection remains effective.
Where suspicion reaches the applicable reporting threshold, follow the jurisdiction's reporting process through the designated officer or function. Suspicious activity or transaction reports generally go to the relevant financial intelligence unit; separate notifications to a gambling regulator may also be required. Reporting terminology, deadlines and thresholds vary.
Protect confidential investigations and observe applicable anti-tipping-off rules. Support agents need approved communication templates that explain account status without revealing a report or sensitive investigative details. Retain records securely for the required period, with access controls and an audit trail.
Measure verification completion, exception rates, review turnaround, repeat document requests and alert quality together. Also monitor complaints and control failures: faster onboarding is not an improvement if it creates compliance gaps.
How to move forward with VertaMatrix
VertaMatrix can support the planning of an iGaming operation across platform infrastructure, payment integrations and licensing advisory. For KYC and AML, the practical starting point is to map your target jurisdictions, products and payment flows, then define how verification providers, transaction data and review workflows should connect to the casino or sportsbook platform. Confirm the scope of supplier responsibilities and integrations before implementation.
Treat the launch plan as a shared operational design, not a promise that technology alone delivers compliance. Agree ownership of policies, investigations, reporting and player communications, then test both straightforward onboarding and difficult exceptions. Your operator remains responsible for meeting its obligations, with specialist compliance and legal advice where needed.
Frequently asked questions
When should an iGaming operator verify a player's identity?+
Verification must occur at the stage required by the applicable jurisdiction, which may be before gambling or before other account activities. Map these requirements into registration and payment controls rather than assuming checks can wait until withdrawal.
What is the difference between source of funds and source of wealth?+
Source of funds explains where the money used for particular transactions came from. Source of wealth explains how the customer accumulated their overall wealth; the evidence needed depends on the risk and applicable requirements.
How can operators reduce KYC friction without weakening compliance?+
Use clear instructions, reliable verification methods and targeted requests for missing evidence. Avoid duplicate requests, provide accessible manual-review routes and measure player experience alongside compliance outcomes.
Let's plan these steps together.
Share your target market and timeline, and we will map out the right launch model and roadmap for you.
Talk to an expertRelated guides
All guides → Licensing
How to Obtain a Betting and Casino Licence: A Guide
Learn how to choose a gambling jurisdiction, prepare your application, structure your business and plan compliance for a casino or sportsbook launch.
 Casino
How to Launch an Online Casino: An Operator Roadmap
Plan your online casino launch with practical steps for licensing, platform selection, games, payments, staffing, testing and responsible gambling.
 Guide
How to Launch a Sports Betting Site: An Operator Guide
Plan your sportsbook launch with practical guidance on platforms, licensing, odds, risk, payments, marketing and the first months of operations.